Medical school debt can make mortgage planning feel complicated, even when a physician has strong…
Jumbo Loans: Requirements High-Net-Worth Borrowers Should Know
Buying a property that sits well above standard loan limits can open up opportunity, but the financing process tends to look a little different once you cross over into jumbo territory. Jumbo loans are mortgages that exceed conforming loan limits set by federal agencies, requiring higher qualifying criteria and specialized underwriting. In this guide, we’ll help you understand how jumbo loans work, what lenders are typically looking for, and how high-net-worth borrowers in areas like Rochester, Buffalo, and Saratoga Springs can prepare for a smooth process.
Key Takeaways
- Purpose: Jumbo loans provide financing options for property purchases that exceed conforming loan limits.
- Requirements: Lenders typically require higher credit scores, substantial assets, and detailed income documentation for jumbo financing.
- Documentation: Expect more thorough underwriting and asset verification compared to standard loan programs.
- Best For: Jumbo loans are designed for buyers with significant financial resources, often purchasing luxury properties, larger homes, or investing in high-cost markets.
Quick Answers: Jumbo Loan Highlights
- What is a jumbo loan? A jumbo loan is any mortgage above the county’s conforming loan limit, requiring non-conforming underwriting.
- Is a larger down payment required? Often, yes; lenders may require larger down payments than for standard loans, though the specifics vary by program and scenario.
- Can investment properties qualify? Yes, many programs support second homes and investment properties, but requirements are often stricter than for primary residences.
- How long does the process take? Underwriting can be more involved, but timelines are similar to other mortgage transactions—plan for extra time to document complex assets or income streams.
What Makes a Loan “Jumbo”?
Jumbo loans step in when the desired loan amount outpaces the conforming loan limits approved by Fannie Mae and Freddie Mac. These limits change yearly and vary by county, but generally, a “jumbo” loan means financing that falls outside guidelines for standard government-backed mortgages. At Haus Capital Corporation (NMLS# 1549644), we work with jumbo lenders offering a range of tailored financing solutions—for both high-net-worth clients financing primary homes and investors working with larger portfolios.
Typical Jumbo Loan Requirements
Borrowers considering jumbo financing will find that qualification standards are elevated across several touchpoints. Lenders want to see:
- Higher credit scores: While requirements vary, many jumbo lenders look for strong credit—often in the mid-to-high 700s or above.
- Robust income and asset documentation: Expect to provide recent tax returns, W2s or K-1s, account statements, proof of liquid funds, and possibly documentation of business or investment income streams.
- Substantial reserves: Lenders often require significant post-closing reserves, sometimes equaling several months of principal, interest, taxes, and insurance (PITI).
- Thorough documentation: Asset verification tends to be more rigorous, especially for clients with diverse or complex holdings.
- Larger down payments: It’s common for jumbo programs to prefer down payments above what’s permitted for conforming loans, although exact requirements depend on loan size, occupancy, and lender guidelines.
Jumbo Underwriting: What to Expect
Jumbo loans aren’t governed by the standard automated guidelines used for most conventional loans. Instead, underwriting is more hands-on and considers the specific risk profile of your scenario. For high-net-worth individuals and real estate investors, this can be an advantage—lenders may accept alternative asset or income documentation if it’s well supported and makes sense in context.
That’s why we emphasize personalized guidance throughout the process. Whether you’re moving up in Rochester or expanding your real estate footprint across Western New York or Florida, it pays to organize your documents and clearly present your financial story at the start.
Primary Homes, Second Homes, and Investment Properties
Jumbo financing isn’t just for owner-occupied homes. Many programs also accommodate:
- Second Homes: Vacation or seasonal residences in markets like Saratoga Springs or coastal Florida.
- Investment Properties: If you’re considering a higher-value acquisition for rental or portfolio expansion, jumbo loans (and specialty programs like DSCR loans) can provide flexible options—though extra scrutiny on rental income or reserves is common.
- New Construction: You can often use a construction home loan structured at jumbo levels to finance building a luxury or custom property.
Asset-Based & Alternative Documentation Solutions
Some high-net-worth borrowers have significant assets but less traditional incomes—think business owners, entrepreneurs, or investors with passive income streams. In these cases, certain lenders may offer bank statement programs or asset-based underwriting where income is calculated from cash flow or asset liquidation strategies. Qualification details can vary, but if you’re in this category, let’s explore your options early, as guidelines and processes can look different than standard jumbo loan routes.
Interest Rates and Loan Structure
Rates for jumbo loans are set by individual lenders and move with current market conditions—they aren’t tied to the conforming loan programs. Your rate and terms will reflect risk, loan size, property type, and your financial profile. Both fixed and adjustable-rate options are available, often with a range of repayment period choices to suit your goals.
How to Prepare for a Jumbo Loan Application
- Gather documentation: Collect recent tax returns, all pages of asset and bank statements, business documentation if applicable, and details on any properties you currently own.
- Clarify your income picture: Be prepared to show how you earn and manage funds, especially if income is distributed across multiple sources.
- Discuss reserves and liquidity: Plan to document retirement accounts, brokerage statements, and liquid assets—underwriters may count these as reserves.
- Connect with your advisor: At Haus Capital, we’ll review your full scenario and recommend the path that supports your larger strategy, whether that’s building, buying, or investing.
Jumbo vs. Conforming Loan Comparison
| Feature | Jumbo Loan | Conforming Loan |
|---|---|---|
| Loan Amount | Above conforming loan limits (varies by county) | Up to conforming loan limit |
| Down Payment | Often higher, varies by lender | Can be as low as 3% for some programs |
| Documentation | Full documentation, enhanced scrutiny | Standard documentation, automated approval |
| Reserve Requirements | Significant, often several months of PITI | Usually less, depends on program |
Your Next Steps: Begin with a Conversation
Every jumbo loan scenario is unique, and requirements often reflect both your financial profile and your larger financing goals. Whether you’re focused on acquiring a luxury residence, purchasing or refinancing in Rochester, growing your investment portfolio, or building from the ground up, the foundation of a successful jumbo loan transaction is clear communication and preparation.
If you’d like to explore your options or walk through a detailed pre-approval plan, reach out to our team by call, text or email. At Haus Capital, we’re committed to financing every opportunity—let’s find the right strategy together so you can move forward with clarity and confidence.
Frequently Asked Questions
Can jumbo loans be used for refinancing, or just for purchases?
Jumbo loans can be used for both purchasing and refinancing properties above conforming loan limits. The requirements for a jumbo refinance are similar to a purchase, including documentation, credit, and appraisal of the property value.
How do jumbo loan reserve requirements work if I have significant investments?
Lenders will review statements from investment, retirement, and bank accounts to verify that reserves meet their guidelines. Some may allow the use of certain retirement or brokerage account balances as part of your reserves, but guidelines vary by lender.
Are there restrictions on the types of property eligible for jumbo financing?
Jumbo loans typically support a range of property types, including single-family homes, some condos, second homes, and investment properties. Special considerations or additional documentation may be required for properties with unique characteristics or mixed-use features.
Can business income or distributions be used to qualify for a jumbo loan?
Yes, many jumbo lenders will accept business income, but will want to see supporting documentation such as tax returns, K-1s, and profit and loss statements. The more complex your financial structure, the more thorough the underwriting process will be.
Is mortgage insurance required on jumbo loans with lower down payments?
Unlike some conforming loans, most jumbo programs do not offer private mortgage insurance. If your down payment is below traditional thresholds, the lender may adjust pricing, structure, or reserves rather than requiring mortgage insurance.
About the Author
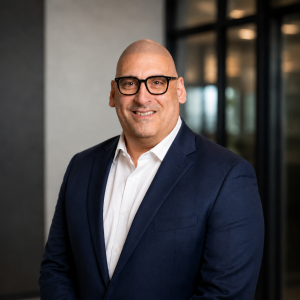
Samuel J DiPiano
Founder & CEO / Mortgage Loan Originator at Haus Capital Corporation · NMLS #57865
Sam DiPiano is the Founder and CEO of HAUS Capital Corporation and a licensed Mortgage Loan Originator. He helps homebuyers, homeowners, and real estate investors navigate residential mortgage financing, with experience across conventional, government, non-QM, DSCR, investment property, and other financing solutions.
Specializes in: Conventional Loans, Jumbo Loans, Investment Property Loans
Licensed in: FL, MI, NY, OH, PA, SC
Related Posts