New York Mortgage Broker
Licensed mortgage broker serving homebuyers across New York. Get matched with the right loan program for your situation.
Honest pricing, clear guidance, and a local team that picks up the phone — from first question to final signature.
Loan Types We Specialize In
Explore the loan programs available to New York home buyers and homeowners.
Cities We Serve in New York
Explore local mortgage guidance for communities across New York.
Serving Homebuyers Across New York
At Haus Capital, we help clients across New York secure tailored financing solutions for a broad range of property types and situations. Whether you’re looking to purchase your first home in the Hudson Valley, refinance in Westchester, invest in a Brooklyn brownstone, or explore options for a vacation retreat in the Adirondacks, our team brings experience and personalized guidance to each conversation. We work with many loan programs—Conventional, FHA, VA, Jumbo, DSCR, Non-QM, and more—to help you explore your options and find a strategy that aligns with your goals. Every client’s story is different, and we’re here to support yours, wherever you are in New York.
What Buying a Home in New York Is Really Like
Financing real estate in New York means navigating a landscape defined by diversity—of properties, markets, and requirements. In New York City, co-ops and condos are a staple. Condominium purchases require project approval, which means we often coordinate closely with management companies and review building finances, insurance, and owner occupancy. Co-ops bring an additional layer with board packages and financial vetting, so we plan for those timelines from the start.
Brownstones in Brooklyn and multi-family homes in Queens or the Bronx often mean appraisals that focus on condition and rental income potential. In these situations, understanding how projected rents factor into qualifying can make a difference—especially with two- to four-unit properties, which are common in many city neighborhoods.
Move outside the city, and the landscape shifts. In Westchester, Nassau, and Suffolk counties, you’ll find a mix of classic single-family homes and post-war capes. Many of these homes are older, so appraisals often note repairs or updates. In the Hudson Valley or upstate regions, rural properties are more common, and we look at eligibility for programs like USDA loans, especially where acreage and well/septic systems come into play.
Coastal properties on Long Island or along the Hudson River mean flood insurance can be a factor. We help clients understand how elevation certificates and flood zones affect both loan options and insurance requirements. In resort areas like the Catskills and Finger Lakes, financing a second home or seasonal property brings different considerations—sometimes related to occupancy, rental income, or property type.
Across New York, purchase conditions vary. In the city and close-in suburbs, buyers often face multiple-offer situations and tight timelines. Upstate or in smaller towns, sellers may expect more flexibility, but homes may have unique features or rural characteristics that matter during underwriting. Every region brings its own pace, requirements, and opportunities. Our job is to help you anticipate what matters most in your specific search.
How We Help New York Buyers and Homeowners
Clients come to us from all walks of life, each with unique goals. For first-time buyers—whether in Manhattan, Buffalo, or the Hudson Valley—we start with a conversation. We help clarify what’s possible, explain the importance of credit and assets, and walk through programs that support lower down payments or assist with closing costs. Clear communication from the beginning helps set realistic expectations.
When people are moving up, downsizing, or relocating—maybe trading a Brooklyn condo for a house in Westchester or looking for a more manageable property upstate—we help map out how to leverage existing equity and structure the transition. Timing is often crucial, especially when buying and selling at the same time, so we look for bridge or recast options when needed.
Self-employed borrowers, those earning commission, and clients with complex income often have questions about qualifying. We review tax returns, business structures, and cash flow carefully, making sure we can document income in ways lenders accept. For these clients, Non-QM programs or bank statement loans may offer flexibility where traditional programs fall short.
Multi-unit and investment property buyers are a strong part of the New York market, especially in neighborhoods like Crown Heights, Astoria, or parts of Rochester and Syracuse. We work through the specifics—how rental income counts, what reserves are needed, how to approach properties with existing tenants, and which programs fit best for investors or house hackers.
Refinancing is often about improving terms, pulling cash out for renovation, or restructuring to meet new financial goals. We help clients assess whether a refinance makes sense and which options are available given the property and current market conditions.
For buyers in competitive markets—places where homes go quickly and sellers expect strong offers—we help position financing to move as efficiently as possible. We coordinate closely with agents, provide upfront review of complex scenarios, and make sure you’re ready to act when the right home appears.
Every client, every property, and every region in New York brings its own set of considerations. We’re here to listen, offer tailored financing solutions, and help you navigate the path that fits your plans.
Regions We Serve in New York
New York’s regions each bring their own character—and unique financing situations. In New York City, buyers contend with condos, co-ops, and multi-family buildings, often facing layered approval processes and competitive bidding. Brooklyn and Queens are marked by brownstones, row houses, and a high volume of multi-unit properties, where rental income and condition issues can be central to loan approval.
Long Island—both Nassau and Suffolk—features a mix of suburban homes, waterfront properties, and older housing stock. Flood zones and coastal insurance requirements frequently come up, especially closer to the shore. Westchester and Rockland counties offer a blend of classic suburban neighborhoods and historic homes, where appraisals may note needed repairs or unique property features.
Upstate regions, including the Capital District, Hudson Valley, Finger Lakes, and Western New York, see more rural properties, seasonal homes, and larger lots. USDA loan eligibility becomes more common, and we often navigate questions about well, septic, and outbuildings. In resort or vacation areas like the Catskills or the Adirondacks, second homes and investment cabins are a regular part of our financing conversations.
Whether you’re searching in a fast-moving urban market or considering a unique rural property, we help clients understand what’s typical for their area and what to expect from lenders, appraisers, and insurance providers.
Programs Available to New York Buyers
New York State homebuyers have access to programs through the State of New York Mortgage Agency (SONYMA). SONYMA’s Achieving the Dream and Low Interest Rate programs are designed to help first-time buyers with down payment assistance and more flexible qualifying criteria. The Homes for Veterans program is available to eligible military personnel and veterans, offering special terms tailored to their needs.
The Remodel New York program can help buyers finance both the purchase and renovation of homes needing updates—particularly helpful with older properties found in many parts of the state. Neighborhood Revitalization supports purchases in targeted areas, sometimes combining purchase and improvement funds. Conventional Plus offers down payment assistance paired with conventional loan terms, expanding options for buyers who meet certain criteria.
Program guidelines and availability can change, and not all buyers will qualify for every option. We confirm current details and eligibility with each client to ensure the programs we discuss are a good fit for your circumstances.
Talk to Someone Who Knows New York
We built Haus Capital to offer a more responsive and knowledgeable mortgage experience—one where financing every opportunity means listening first. If you’d like to talk through your plans, explore your options, or simply get a sense of what’s possible in New York, we invite you to reach out. You’ll connect with someone who understands the details that matter here and is ready to help you find the right strategy for your next step.
About Haus Capital Corporation NMLS# 1549644
With 19 years of mortgage experience, we specialize in helping homebuyers navigate the mortgage process with confidence. Licensed in FL, MI, NY, OH, PA, SC. Whether you’re buying your first home or refinancing, we’re here to help you find the right loan for your situation.
📞 844-716-HAUS (4287) ✉ info@hauscapitalcorp.com 🌐 https://hauscapitalcorp.com
Frequently Asked Questions
Does the State of New York Mortgage Agency (SONYMA) offer first-time homebuyer programs?
Yes, SONYMA provides a range of programs specifically designed for first-time homebuyers, including down payment assistance and competitive loan options. Eligibility requirements vary, so it's a good idea to review their guidelines and speak with a mortgage broker familiar with SONYMA products.
How do FHA loan limits work in New York City compared to other counties in the state?
FHA loan limits in New York vary by county, and New York City typically has higher limits due to home prices in the area. It's important to check the current limits for your target county to know what loan amount you may qualify for.
Can I use rental income from a multi-family property in Brooklyn to qualify for a mortgage?
Yes, rental income from a two- to four-unit property in Brooklyn or elsewhere in New York can often be used to help you qualify for a mortgage. Lenders will usually require documentation of expected rental income and may have specific requirements for multi-unit properties.
Are there special requirements for buying a condo in Manhattan with a conventional loan?
Conventional lenders in New York, especially in Manhattan, have specific guidelines for condo eligibility, including requirements for the building's financial health and owner-occupancy rates. It's important to verify that the condo project is approved by the loan program you’re considering.
What are my options if I want to buy a fixer-upper in upstate New York?
There are renovation loan programs available in New York that allow you to finance both the purchase and repairs of a fixer-upper in one loan. These programs have specific requirements for the types of repairs and the condition of the property, so consulting with a knowledgeable mortgage broker can help you understand your options.
We pride ourselves on clear communication and easy access when you need us. Answer a few quick questions and an experienced, local professional will guide you from here.
We keep you informed and supported every step of the way.
A quick call with a local advisor is the easiest first step. No pressure, no credit check.
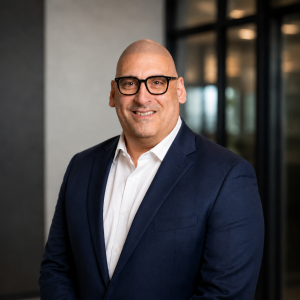
Samuel J DiPiano
Sam DiPiano is the Founder and CEO of HAUS Capital Corporation and a licensed Mortgage Loan Originator. He helps homebuyers, homeowners, and real estate investors navigate residential mortgage financing, with experience across conventional, government, non-QM, DSCR, investment property, and other financing solutions.