Michigan Mortgage Broker
Licensed mortgage broker serving homebuyers across Michigan. Get matched with the right loan program for your situation.
Honest pricing, clear guidance, and a local team that picks up the phone — from first question to final signature.
Loan Types We Specialize In
Explore the loan programs available to Michigan home buyers and homeowners.
Cities We Serve in Michigan
Explore local mortgage guidance for communities across Michigan.
Serving Homebuyers Across Michigan
We work with homebuyers and homeowners throughout Michigan, helping to connect them with tailored financing solutions that fit their needs. Whether you’re purchasing your first home, moving within the state, exploring options for a lakefront cottage, or considering a multi-unit investment, we’re here to help you explore your options. Our team handles a wide range of loan programs, including Conventional, FHA, VA, Jumbo, investment property, new construction, and specialized programs for unique property types. We understand the financing landscape in Michigan and aim to provide clear communication and personalized guidance every step of the way.
What Buying a Home in Michigan Is Really Like
Financing a home in Michigan brings its own set of considerations, shaped by the state’s diverse housing stock and geography. In Metro Detroit, you’ll find classic brick homes built across decades, each with its own quirks. Older homes in places like Grosse Pointe or Royal Oak may bring up appraisal items around condition, so we talk through potential repair requirements and work with lenders who understand these properties. Condominiums are plentiful in downtown Grand Rapids, Ann Arbor, and parts of Oakland County. Here, project approval can be a hurdle—some buildings meet all requirements, others may have issues with occupancy or litigation, so we make sure you know where a property stands before you get too far down the road.
Outstate, especially in northern Michigan and the Upper Peninsula, rural homes are more common. These areas might be eligible for USDA loans, but property types and distance from town can affect eligibility and appraisals. Waterfront homes on the Great Lakes or inland lakes bring another layer—lenders will ask about flood insurance, and sometimes about access and seasonal use. Second homes and vacation properties are a major feature in Traverse City, Petoskey, and along the Lake Michigan shore; these require a different approach than a primary residence, especially when properties are only accessible part of the year or have unique features like shared wells or septic systems.
In university towns like Ann Arbor or East Lansing, two- to four-unit homes are often in demand, both for rental and for owner-occupants who want to offset their mortgage with rental income. It’s important to know how lenders calculate rental income and what documentation is needed, especially when the property has a long rental history or is being converted back to owner-occupancy. Across the state, the pace of the market can range from highly competitive in places like Birmingham or East Grand Rapids, where buyers may need to move quickly and present strong offers, to more measured in rural areas or smaller towns. We help buyers understand what’s realistic, what a competitive offer looks like in their area, and how to navigate local market expectations.
How We Help Michigan Buyers and Homeowners
Every homebuyer or homeowner who comes to us in Michigan brings a different set of circumstances, and we take time to listen and build a strategy around what matters most to them. First-time buyers often want to know what programs they qualify for and how much flexibility they have around down payment and credit. We walk through state and local programs, review documentation requirements, and help set expectations so there are no surprises at closing. For clients moving up, downsizing, or relocating within the state, we look at options for bridging between homes, coordinate timing with other real estate agents, and help plan financing for renovations or upgrades.
Self-employed and commission-earning borrowers make up a significant part of our client base in Michigan. We understand how underwriters look at variable income, business expenses, and tax returns, especially in industries common to Michigan like automotive, healthcare, and independent contracting. We help you organize your documentation, anticipate questions, and find lenders who offer flexibility for unique income situations. Investors and buyers of two- to four-unit properties, particularly in college towns or growing neighborhoods, often want to know how rental income fits in and what options are available for financing multiple properties. We guide you through the details, from cash flow calculations to reserve requirements.
We also work with clients looking to refinance—whether to improve terms, tap into equity, or consolidate debt. We review your goals and current mortgage, then outline the options and what they mean for your budget and long-term plans. For buyers in competitive markets like Ann Arbor or Royal Oak, timing matters. We help coordinate with your agent, ensure your financing is positioned to move quickly, and communicate clearly so you know where things stand. In every situation, our role is to provide personalized guidance, clear communication, and a financing strategy built around your specific needs.
Regions We Serve in Michigan
Michigan’s real estate landscape is as varied as its geography. In Southeast Michigan, Metro Detroit offers a wide mix of classic neighborhoods—think brick colonials in Birmingham, bungalows in Ferndale, and historic homes throughout the Grosse Pointes. Appraisals there often focus on property condition, while multiple-offer situations are common in sought-after districts. In West Michigan, Grand Rapids and its surrounding suburbs see a blend of new construction and revitalized older homes, with condos and townhomes especially popular downtown.
Mid-Michigan, including Lansing and East Lansing, features a strong mix of single-family homes and student-oriented rentals, with two- to four-unit properties frequently in play near university areas. The northern Lower Peninsula, from Traverse City through Petoskey, is known for lakefront homes and seasonal cottages—buyers here often need guidance on second home financing and unique property features like shared driveways or wells. The Upper Peninsula is more rural, with properties that may qualify for special financing based on location and use. Across Michigan, we work with buyers and homeowners in both large cities and smaller communities, bringing experience with the nuances each region presents.
Programs Available to Michigan Buyers
Michigan buyers have access to a range of home financing programs designed to make purchasing more accessible. The Michigan State Housing Development Authority (MSHDA) offers several programs, including MI Home Loan for first-time buyers, which can provide assistance with down payment and closing costs, and MI Home Loan Flex, geared toward buyers with varying income and property types. The Mortgage Credit Certificate (MCC) program gives qualifying buyers a potential benefit at tax time. MSHDA also offers Down Payment Assistance programs, which can be added to certain loans for eligible buyers.
For buyers in rural areas, USDA Rural Development loans can be a fit, while VA loans are available to eligible veterans and active-duty service members statewide. FHA loans remain an option for many buyers who want more flexibility with credit or down payment. Program guidelines and availability can shift, so we always confirm the latest details and requirements for each client. Our goal is to help you understand which options fit your situation and connect you with the right resources for your Michigan purchase.
Talk to Someone Who Knows Michigan
When you reach out to us, you’ll talk with someone who understands the ins and outs of Michigan home financing. We built this business to offer a more responsive and knowledgeable experience, and we’re here to listen to your goals and help you find the right strategy. Let’s start a conversation—no pressure, just straightforward answers and real local insight.
About Haus Capital Corporation NMLS# 1549644
With 19 years of mortgage experience, we specialize in helping homebuyers navigate the mortgage process with confidence. Licensed in FL, MI, NY, OH, PA, SC. Whether you’re buying your first home or refinancing, we’re here to help you find the right loan for your situation.
📞 844-716-HAUS (4287) ✉ info@hauscapitalcorp.com 🌐 https://hauscapitalcorp.com
Frequently Asked Questions
What first-time homebuyer programs are available in Michigan through MSHDA?
Michigan State Housing Development Authority (MSHDA) offers programs for first-time buyers, including down payment assistance and special loan options. These programs have specific eligibility requirements related to income, credit, and property location.
Can I use rental income from a duplex in Wayne County to help qualify for a mortgage?
Yes, lenders in Michigan may allow you to use projected rental income from a two-unit property, like a duplex in Wayne County, to help you qualify. You’ll need to provide documentation and meet specific lender and program guidelines.
What are the requirements for buying a lakefront cottage as a second home in Michigan?
To buy a lakefront cottage as a second home in Michigan, you’ll need to meet lender requirements for second or seasonal homes, which can differ from those for primary residences. These requirements typically include stricter credit and down payment standards.
Does the FHA have different loan limits in Michigan counties like Oakland or Kent?
FHA loan limits in Michigan can vary by county, so areas like Oakland or Kent may have different maximum loan amounts. Your broker can help you determine the current limit for your specific location and property type.
Are there special considerations for getting a mortgage on an older home in Michigan that needs repairs?
Yes, if you’re buying an older Michigan home that needs repairs, some loan programs allow you to finance renovation costs into your mortgage. Lenders may also require certain repairs to be completed before closing, depending on the property’s condition.
We pride ourselves on clear communication and easy access when you need us. Answer a few quick questions and an experienced, local professional will guide you from here.
We keep you informed and supported every step of the way.
A quick call with a local advisor is the easiest first step. No pressure, no credit check.
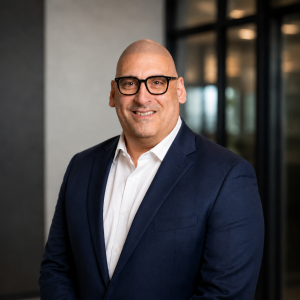
Samuel J DiPiano
Sam DiPiano is the Founder and CEO of HAUS Capital Corporation and a licensed Mortgage Loan Originator. He helps homebuyers, homeowners, and real estate investors navigate residential mortgage financing, with experience across conventional, government, non-QM, DSCR, investment property, and other financing solutions.